
BANK ON LIVING
Adam Stewart of Compound Wealth reveals the four retirement regrets he sees time and time again.
Adam Stewart of Compound Wealth reveals the four retirement regrets he sees time and time again.
PHOTO DEBORAH DE GRAAF
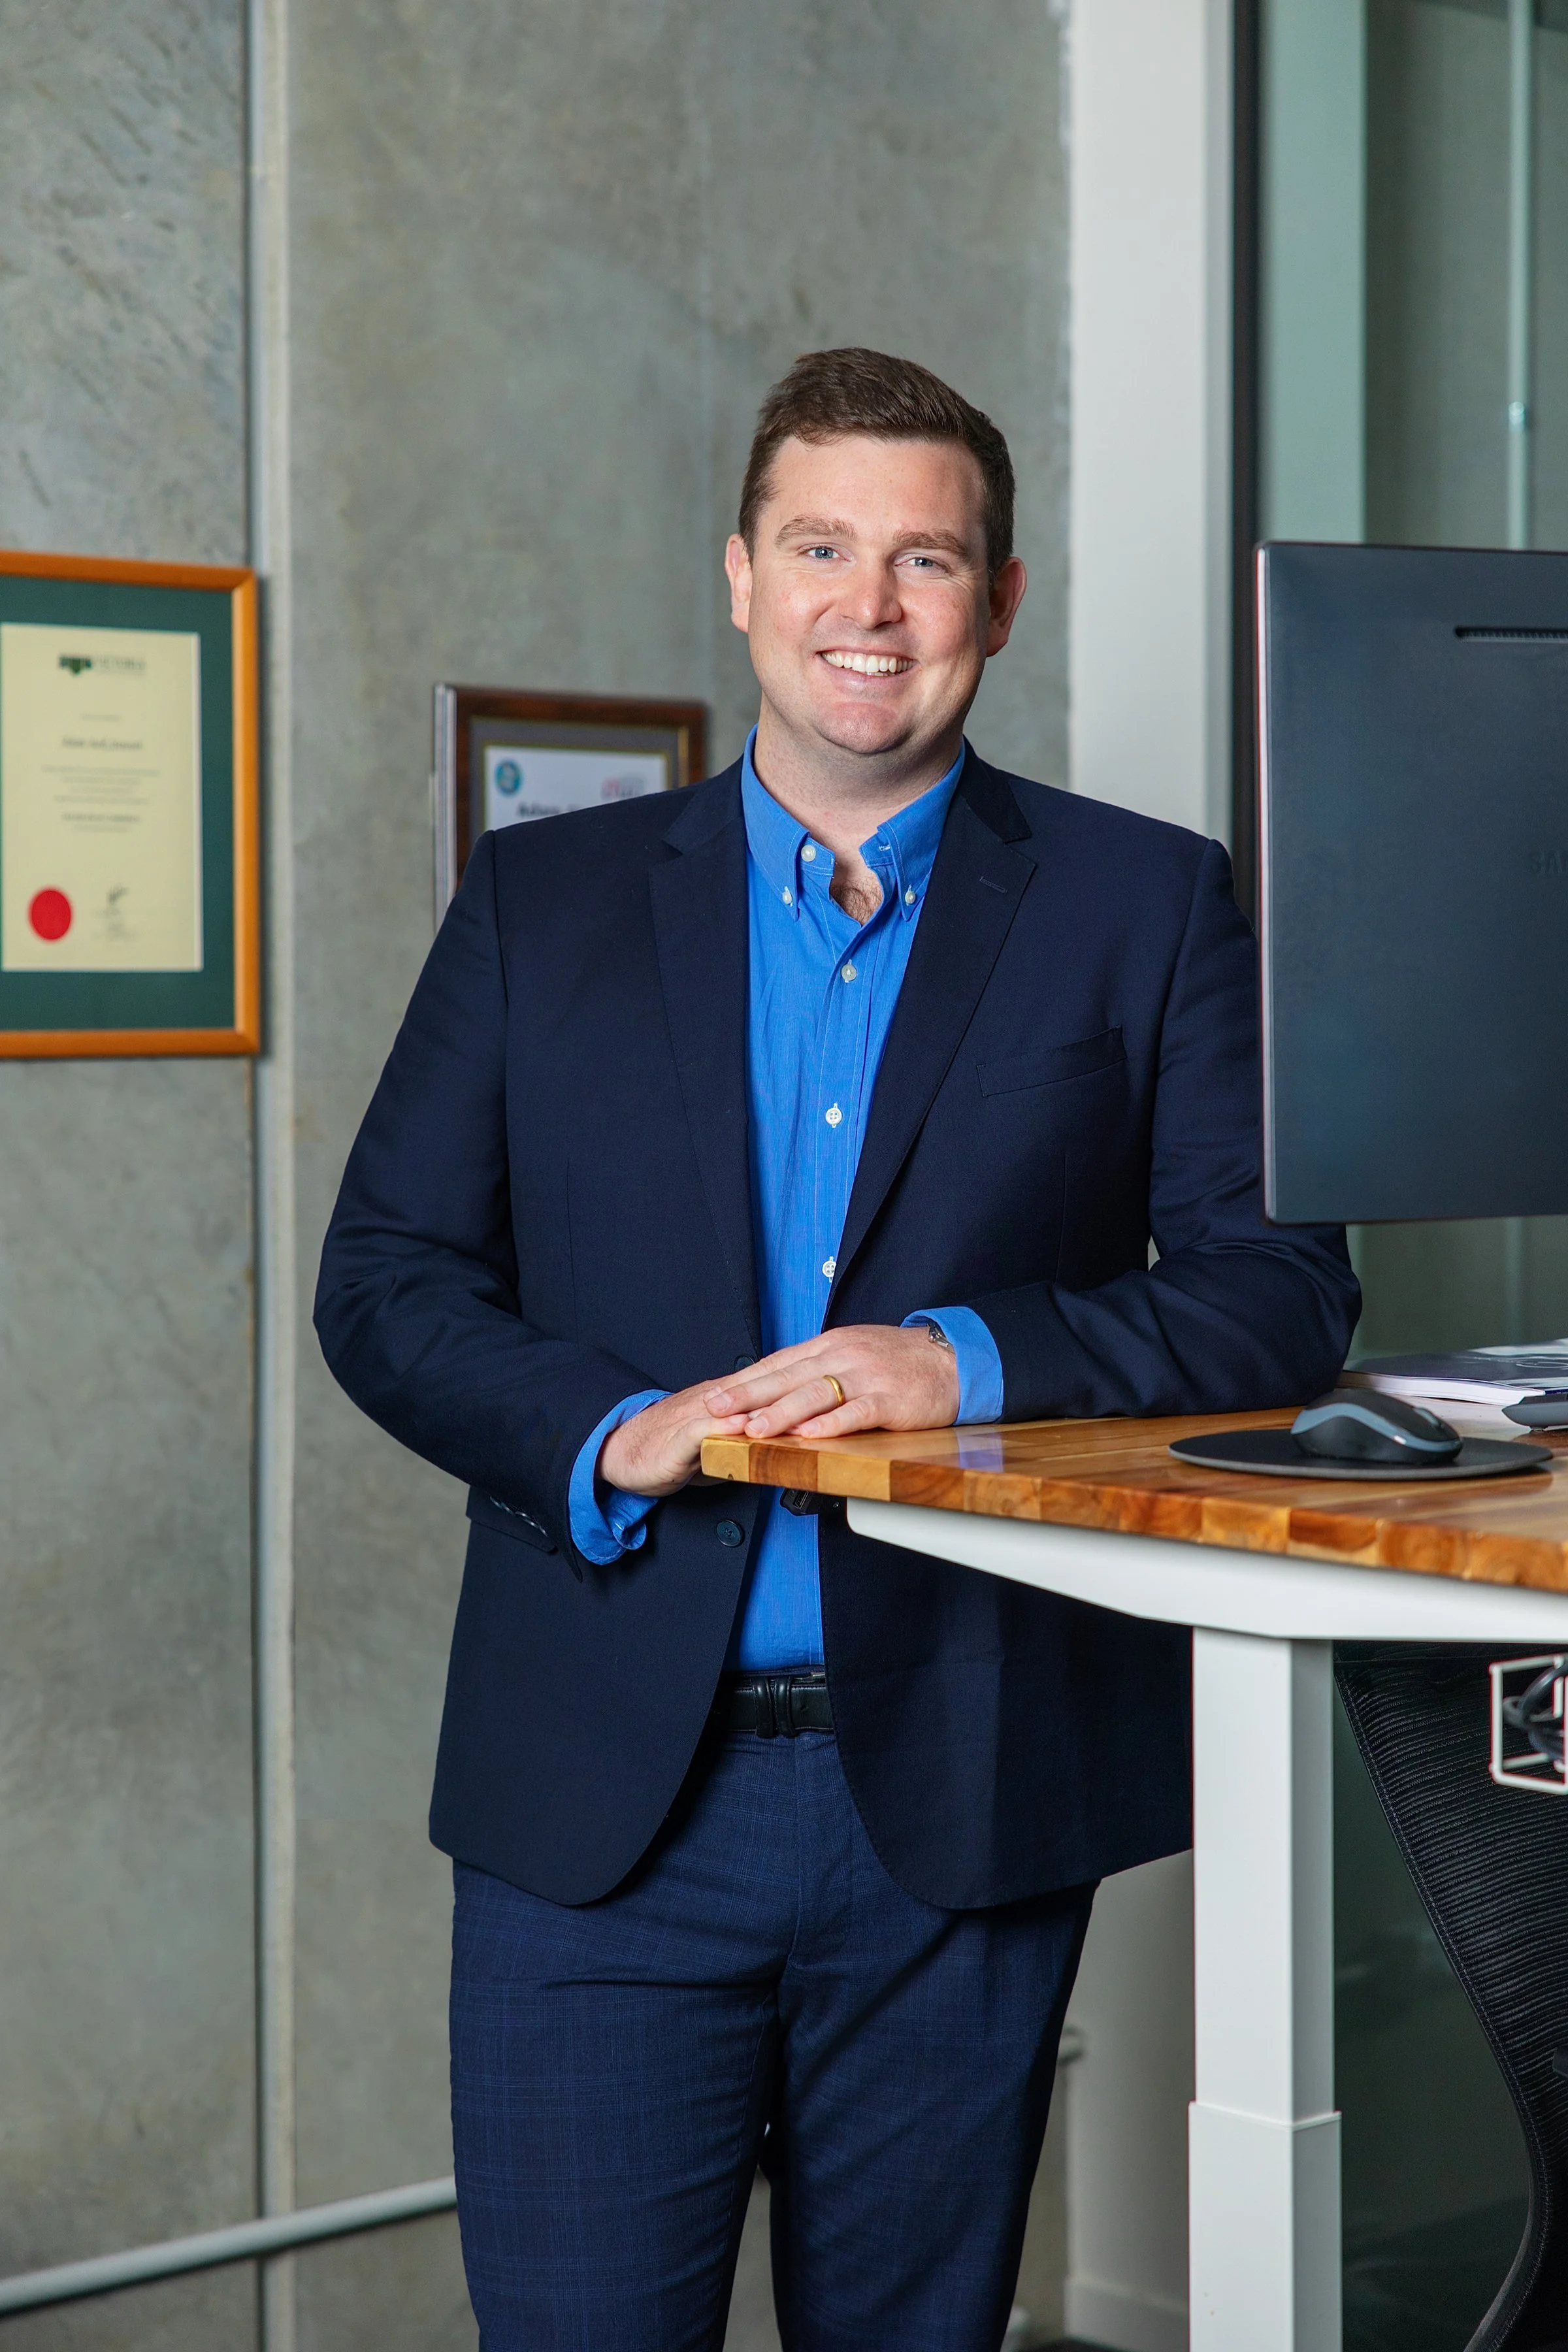
I’ve spent years sitting across the table from Kiwis planning their retirement, and one thing I’ve noticed is that the regrets tend to sound the same.
The first is waiting too long to stop. People work hard and do everything ‘right’, then retire late, only to find their health or energy has already slipped away. I think of my own father here. He passed in his early sixties, and was a hard worker by choice, but there were trips he talked about and never took. I’ve learned through others that retirement’s a window that’s worth protecting.
The second regret is not spending enough early enough. I read Die With Zero by Bill Perkins this year and it put words to something I already believed, which is that most of us are too cautious during the years we’re healthiest and most capable of enjoying what we’ve built. I’ve watched people leave money behind and a bucket list unfinished. To be clear, spending well doesn’t mean ending up with nothing. It means bringing some of that spending forward into the years in which you can enjoy it most.
Third is not tracking progress early enough. This one usually surfaces as anxiety. People ask, “Have I done enough?” and “Can I actually stop?” Without visibility over where you stand, you either over-save and miss out on living now, or under-save and carry that stress for years. The clients who feel calmest are the ones who defined early what a meaningful life actually looks like to them, then built a plan toward it for the years leading into retirement.
The fourth regret is leaning on KiwiSaver alone. Kiwisaver’s a solid tool, but it’s not a full strategy, because you can’t touch it before age 65 unless you’re buying a first home. Investing outside KiwiSaver gives you flexibility. You can access income earlier if you want it, and decisions are made on your terms, rather than your Kiwisaver scheme’s.
Here in the Mount, I meet plenty of people who’ve done the sensible thing their whole lives. The biggest regret I see among them is a missed life. If you’re able to retire part-time, take the trip and spend a little more while you’re well. Security matters, but a life well lived alongside it matters more. COMPOUNDWEALTH.CO.NZ

BUILDING FREEDOM
UNO’s new columnist, Mount financial adviser Adam Stewart, shares his grounded, practical approach to investing, retirement and financial freedom.
UNO’s new columnist, Mount financial adviser Adam Stewart, shares his grounded, practical approach to investing, retirement and financial freedom.
PHOTOS DEBORAH DE GRAAF
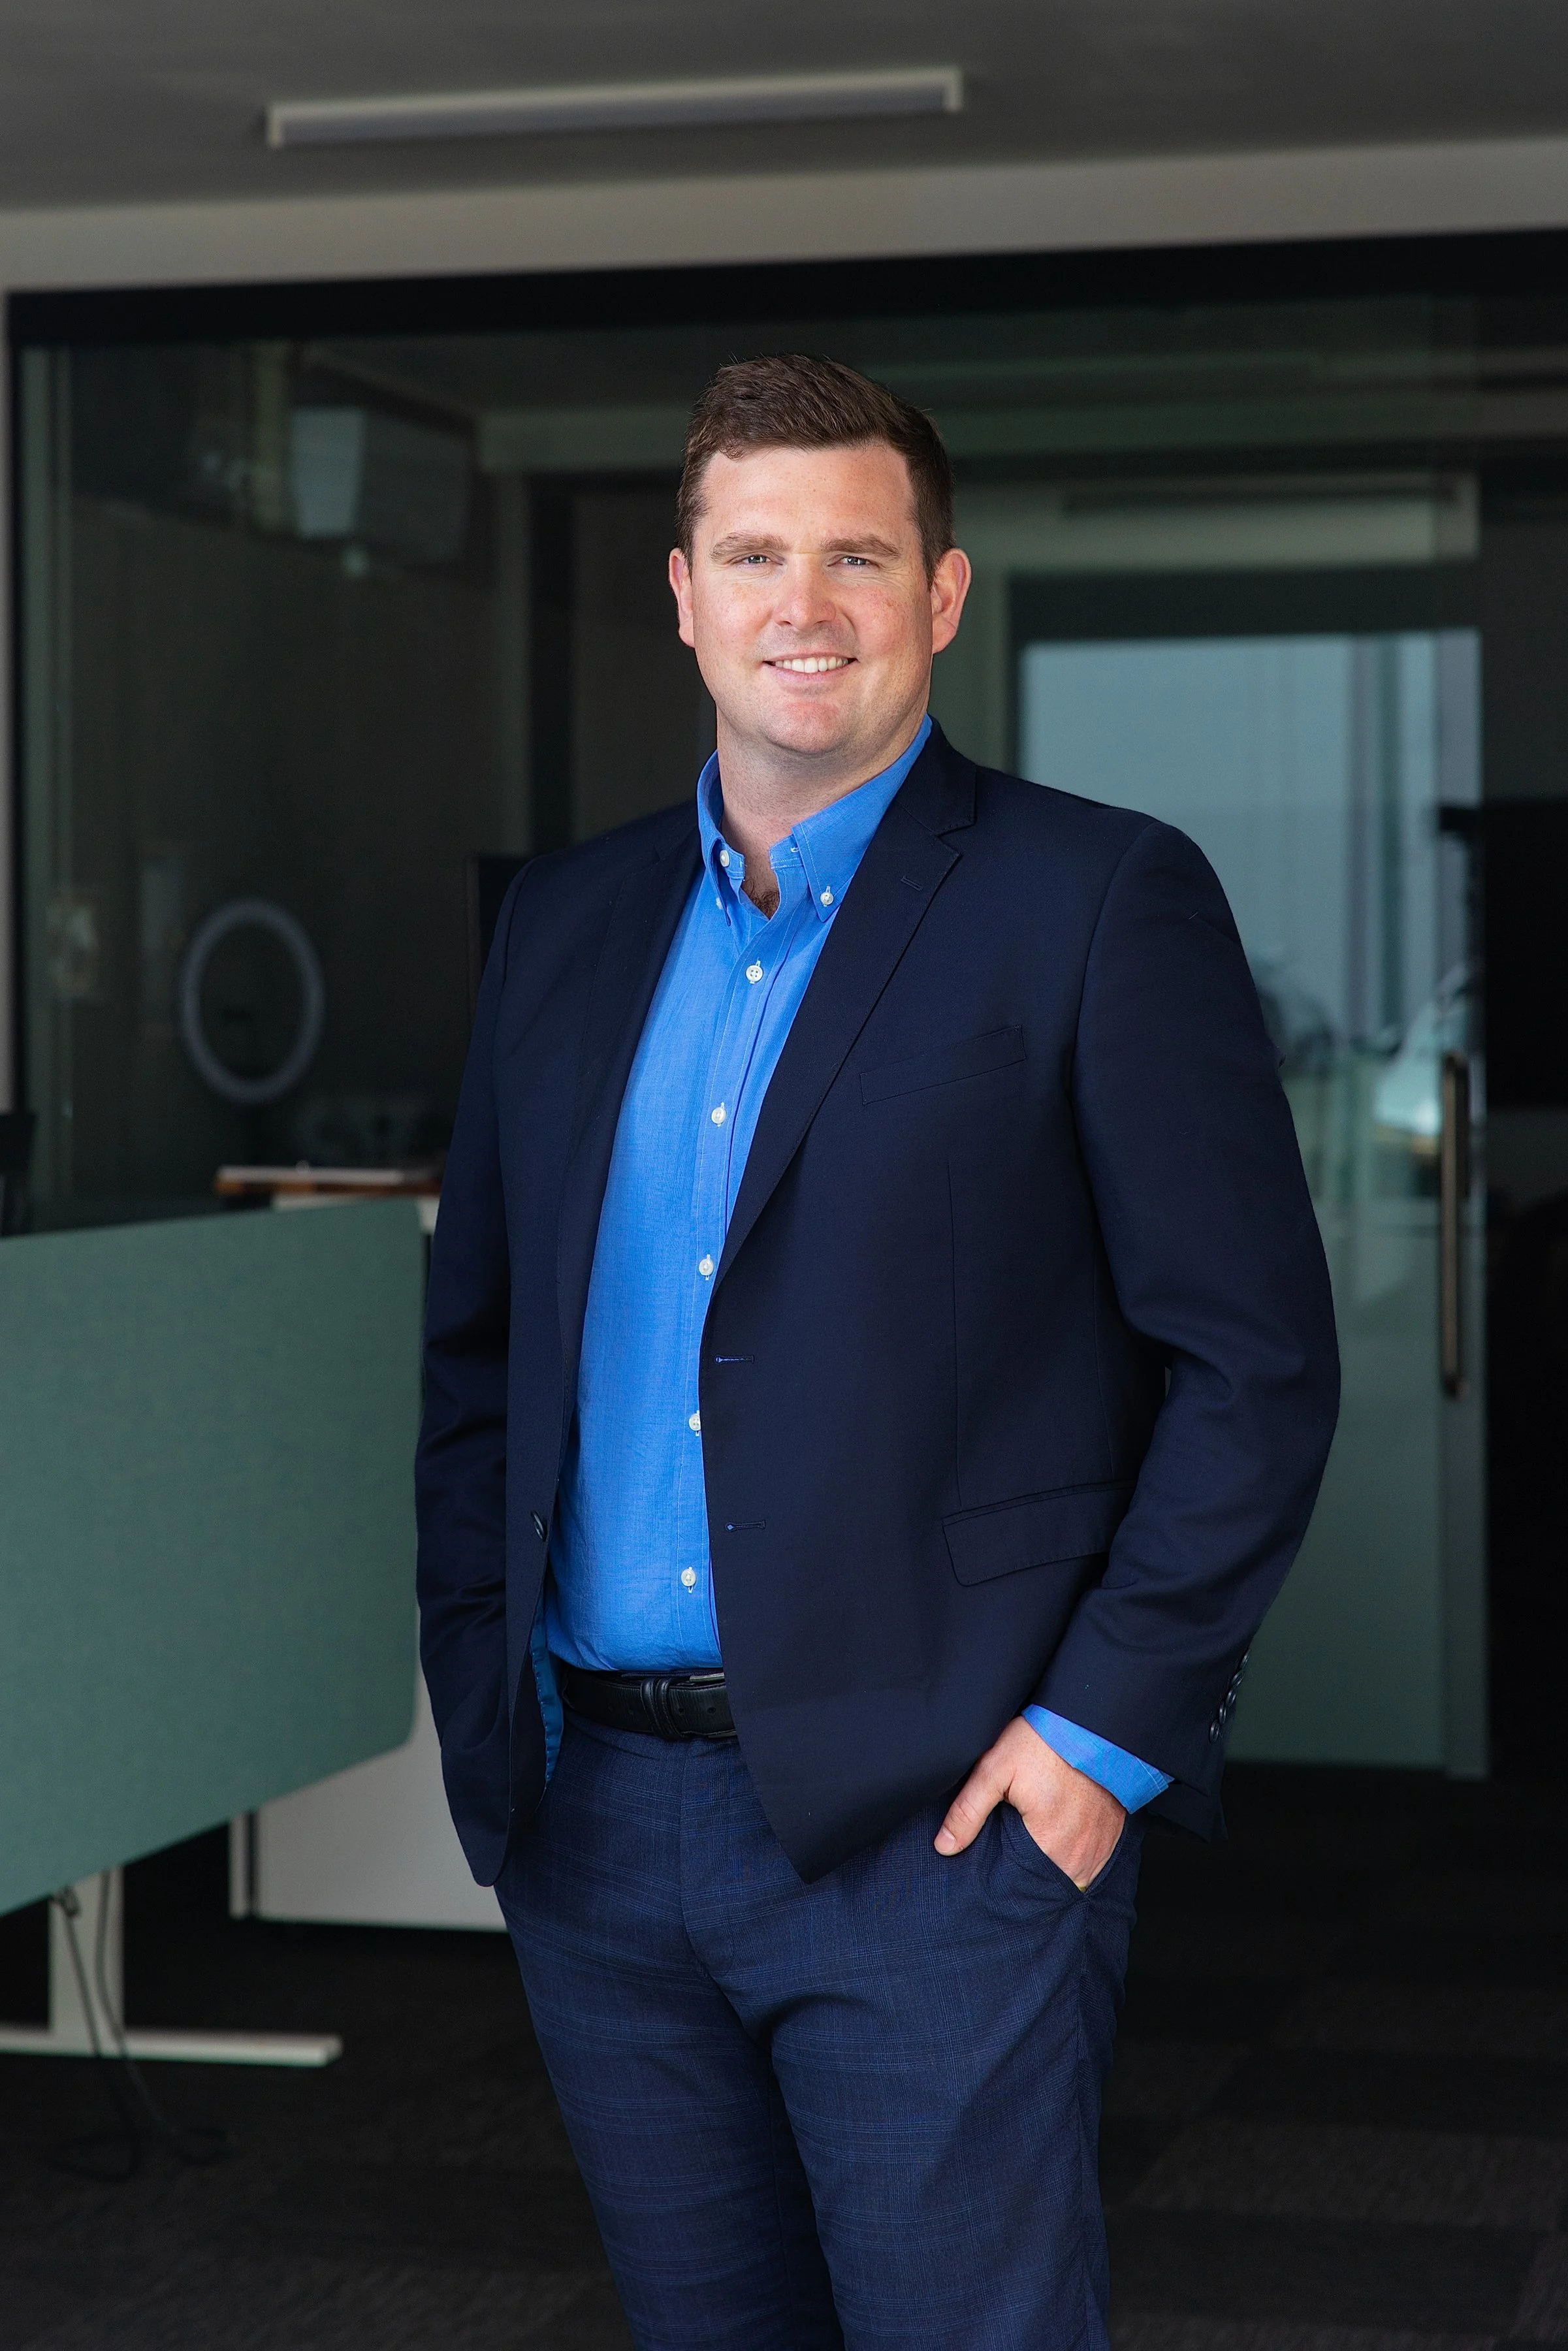
At 32, Compound Wealth founder Adam Stewart has already spent more than a decade immersed in the world of investing, KiwiSaver and financial planning. But despite managing more than $170 million in funds under advice and working with clients across New Zealand, his approach to wealth remains surprisingly grounded.
Raised on a dairy farm in Ashburton, Adam says growing up in a hardworking farming family shaped much of how he thinks about money and long-term security. “There’s no such thing as days off on a farm,” he says. “The cows still need milking on Christmas Day.”
His parents’ work ethic left a lasting impression. So too did the realities of farm ownership, with debt, weather dependence and the relentless pressure that can come with running a business tied so closely to the land.
“I saw a lot of toil from my parents,” he says. “I think that got me thinking about how I could do things in a smarter way.”
That curiosity eventually led him to study finance and commercial law at Victoria University in Wellington, where he landed a part-time role at a financial planning firm while still in his teens. It was there, while working on matters related to the relatively new KiwiSaver, that something clicked. “I got really passionate about KiwiSaver because I understood the power of compound interest.”
Like many people who eventually end up in finance, Adam says he was also drawn to the idea of independence. Reading Rich Dad, Poor Dad at a young age sparked an interest in financial freedom and business ownership, concepts that would later become central to both his career and personal philosophy.
After university, Adam worked for a government-appointed default KiwiSaver provider, eventually moving into a role in which he travelled the country advising financial advisers on investment products and KiwiSaver strategies. The experience exposed him to a huge range of financial businesses – the good, the bad and everything in between.
But it was conversations outside the office that inspired him to launch Compound Wealth. “I’d be at the rugby club or out socially and people would ask me what KiwiSaver fund they should be in,” he says. “I just assumed most people knew what they were doing financially, but they didn’t.”
What shocked him most was not a lack of intelligence, but a lack of guidance. “I was meeting CEOs, lawyers, accountants and people with two or three hundred thousand dollars sitting in the wrong fund.”
At just 24, Adam started Compound Wealth with the simple goal of helping ordinary New Zealanders make better long-term financial decisions. Initially, much of that work centred around KiwiSaver and moving clients into funds that better matched their goals and risk tolerance. Over time, however, the business evolved into retirement planning, investment strategy and helping clients create lives that feel financially secure.
Today, Adam’s typical client is approaching retirement or already retired, often with more than $1 million in investments, property or KiwiSaver assets. “A lot of people have worked extremely hard for decades, but they don’t actually know how to spend their money confidently,” he says.
It is a surprisingly common problem. Adam says many retirees remain overly conservative with their investments, worried they’ll run out of money. Others hold onto wealth purely out of fear.
“Too many people think they need to die with exactly the right amount left over,” he says. “But often they could afford to enjoy life a lot more.”
Instead of simply focusing on investment returns, Adam says much of his work now revolves around helping clients align their money with the lives they actually want to live. That might mean helping someone structure their finances so they can travel more in their 60s and 70s, give money to their children earlier, or feel comfortable spending what they’ve spent decades building.
“If you want to take the family to Fiji and pay for everyone because you can afford to do it, great,” he says. “If you want to help your kids get ahead while you’re still around to see the benefit of it, great.”
Adam’s philosophy around investing itself is notably measured. Rather than chasing hot stock tips or market timing, he advocates for low-cost diversified investing and long-term thinking.
“We’re not trying to pick the needle in the haystack,” he says. “We own the haystack.”
It’s advice he applies to his own life. Adam started Compound Wealth in his mid-20s, while living rent-free back in Ashburton and playing Heartland rugby. The early years were difficult. He admits earning trust as a young adviser came with “a lot of hard knocks”.
“People would think, ‘Who’s this 24-year-old advising me on my finances?’” he laughs.
Still, he kept showing up. Over time, the business grew steadily, helped in part by the digital shift brought on by COVID-19, which accelerated online financial advice across New Zealand.
Now based in Mount Maunganui with his wife and young family, Adam has built both the lifestyle and the business he once imagined for himself. He sponsors local rugby and tennis clubs, and works from a modern Mount office. He says maintaining balance remains important.
“I don’t want to build some huge corporate monster. I enjoy my lifestyle. I try to live the way I teach my clients to live.”
That may be the core philosophy underpinning both Adam Stewart and Compound Wealth. Financial planning is not really about money at all.
“Financial freedom,” he says, “is having the ability to do what you want, when you want, with the people you care about.” COMPOUNDWEALTH.CO.NZ